Global Branded Residences Report: August 2026 Trends
branded.homes Research Team
Market Intelligence & Advisory
Share
Global Branded Residences Report August 2026. Analyze growth across Spain, Dubai, and Montenegro as the sector shifts toward service and scarcity.
Global Branded Residences Week Report: August 3, 2026
The branded-residences sector is entering the second half of 2026 with a broader geographic footprint and a more sophisticated buyer proposition. The market is no longer defined only by hotel-branded towers in Dubai or resort villas in the Caribbean. It now includes wellness-led communities, branded urban apartments, automotive and fashion collaborations, and mixed-use destinations where hospitality operations are part of the asset’s long-term value.
Savills’ 2025/26 market research captures the direction of travel: 25 countries are offering their first branded-residential project, alongside 39 new hotel brands and 19 non-hotel brands entering the category. That expansion is important, but it also makes selection more difficult. Investors must now distinguish between a genuine operating platform and a marketing label.
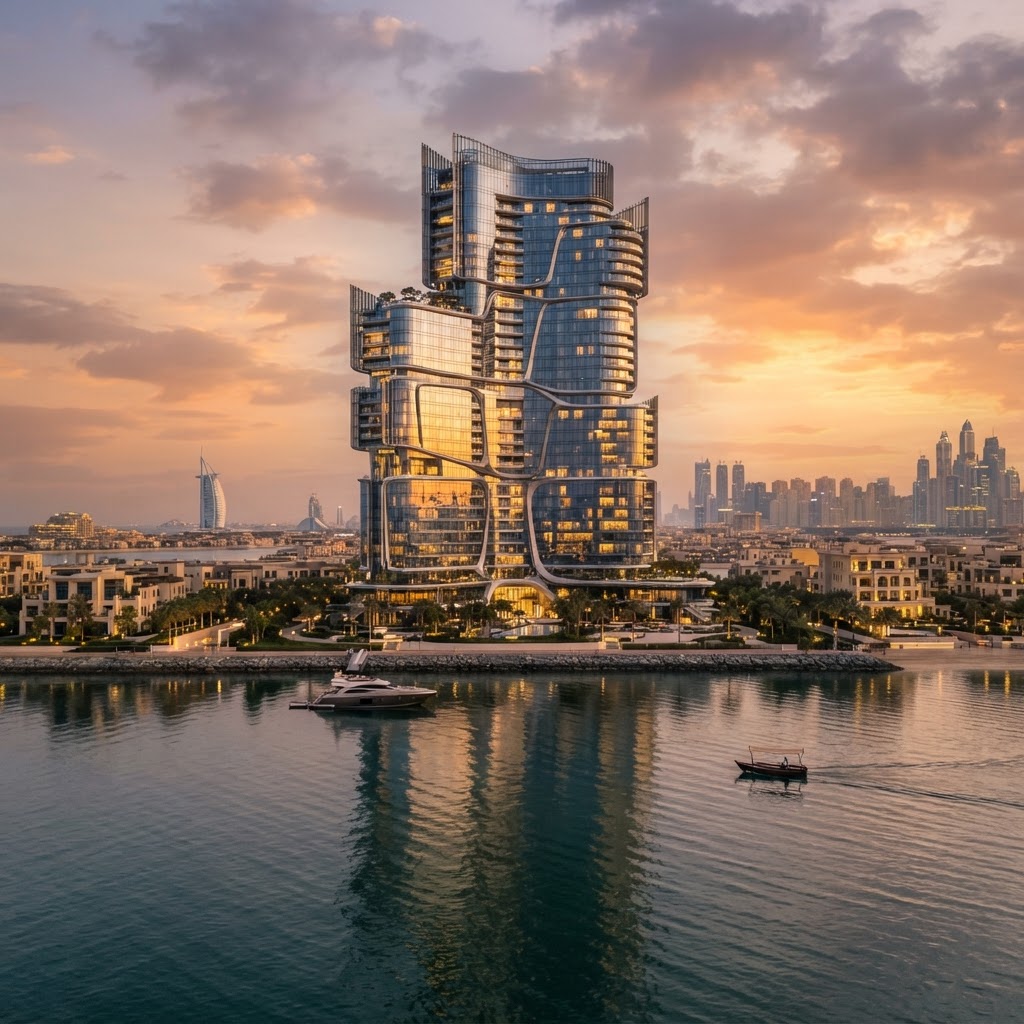
Dubai: scale, liquidity and a premium for execution
Dubai remains the benchmark market for volume, international demand and delivery confidence. Its branded-residential pipeline spans established hospitality names, ultra-luxury hotel operators and automotive brands. Buyers continue to value the combination of freehold ownership, global connectivity, professional rental management and a deep resale audience.
The strongest projects are increasingly differentiated by operations rather than architecture alone: arrival experience, concierge depth, wellness infrastructure, private-club access and the credibility of the hotel operator. In a market with substantial new supply, execution and handover quality are becoming more important than headline branding.
Dubai’s investment case remains strongest for buyers who prioritize liquidity and a clear international exit market. The principal risks are supply concentration, off-plan delivery timing and paying a premium that is not supported by durable service standards.
Spain and Portugal: Europe’s urban-resort convergence
Spain continues to lead Europe in urban branded-residence activity, while Portugal is building a compelling pipeline around golf, coastal wellness and integrated resort destinations. The two markets are increasingly complementary: Madrid, Barcelona and the Costa del Sol provide urban and lifestyle liquidity, while Portugal’s Comporta, Algarve and other resort corridors offer scarcity and longer-stay demand.
Savills notes that Spain and Portugal are closely matched in completed and pipeline projects, with Spain leading in urban schemes. Portugal’s opportunity is more concentrated: a smaller number of carefully positioned developments can create a stronger scarcity narrative when paired with an experienced hotel operator.
For investors, the key diligence questions are rental-pool mechanics, management fees, non-resident financing, construction quality and the relationship between private use and income generation. The best European projects are selling a managed ownership experience, not simply a branded apartment.
Mexico: depth across multiple luxury corridors
Mexico is one of the most diversified branded-residence markets in the Americas. Its opportunity set extends from Riviera Maya and Los Cabos to Puerto Vallarta, Punta Mita and Mexico City. The market benefits from strong North American buyer awareness, established tourism infrastructure and a wide range of price points.
Riviera Maya remains particularly relevant for resort-led residences, where owners can combine personal use with professionally managed rental demand. Mexico City adds a different proposition: urban branded residences linked to dining, culture, business travel and long-term local wealth.
The market’s main challenge is dispersion. A recognized brand cannot compensate for weak access, oversupply in a micro-market or an unclear rental program. Buyers should underwrite the destination first, then the operator, and only then the brand premium.
Montenegro: a scarcity market moving toward institutional standards
Montenegro continues to attract attention because its coastline offers limited, visually distinctive inventory and growing international recognition. Porto Montenegro and the Bay of Kotor have helped establish the country as a premium Adriatic destination, while new hospitality and branded-living concepts are raising expectations for service and asset management.
Montenegro’s appeal is scarcity rather than scale. That can support pricing when a project has a genuinely exceptional waterfront position, credible infrastructure and year-round destination programming. It also creates risk: a short summer season, limited resale depth and inconsistent operating quality can materially affect returns.
The investment thesis is therefore selective. Projects with a strong hotel partner, a complete marina or resort ecosystem and transparent rental-pool terms deserve attention; isolated apartments with a logo do not.
Dominican Republic: the resort model gains institutional depth
The Dominican Republic is becoming one of the Caribbean’s most active branded-residence markets. Marriott’s presence illustrates the trajectory: two projects are open and a further six are reported in the pipeline. The broader market is supported by resort development, airport connectivity, North American demand and the ability to package residences with hotel services.
The strongest opportunities are likely to come from mixed-use communities rather than standalone buildings. Owners benefit when a residence is connected to restaurants, beach clubs, golf, wellness and a professionally managed hospitality operation. For investors, occupancy assumptions should be tested against seasonality, competing room supply and the exact revenue-sharing formula.
The Dominican Republic offers attractive growth potential, but the underwriting must be operationally disciplined. Construction progress, title, hurricane resilience, insurance and the developer’s delivery history are as important as the brand name.
What buyers should watch in August
Three themes are shaping the market. First, scarcity is becoming a design and operating strategy: smaller inventories, stronger wellness concepts and more distinctive locations are commanding attention. Second, non-hotel brands are expanding the category, but their value depends on whether the collaboration creates a credible lifestyle ecosystem. Third, buyers are becoming more demanding about income transparency, service charges and exit liquidity.
The market’s next phase will reward projects that deliver three things simultaneously: a defensible location, a professional operator and a service experience that remains consistent after the sales launch. Branding can accelerate demand, but only execution protects value.
Investment conclusion
Dubai remains the most liquid and globally legible market in this group. Spain and Portugal offer the strongest European combination of lifestyle demand and maturing operational infrastructure. Mexico provides depth and multiple entry points, while Montenegro and the Dominican Republic offer higher-growth, more selective resort opportunities.
For 2026 buyers, the central question is no longer whether a branded residence carries a premium. It is whether the operator, location and ownership structure are strong enough to earn that premium throughout the holding period.
Market Intelligence
Get the next briefing by email.
branded.homes
The Branded Residences Investor Guide 2026
Free PDF · 16 pages
The Branded Residences Investor Guide 2026
Premium property with hotel-grade living, explained for investors — the premium, the markets, the due diligence, in one free guide.
Instant download. No spam.
Written by
branded.homes Research Team
Market Intelligence & Advisory
Related Projects
Branded residences connected to this article


Related Articles
Continue exploring market insights
Subscribe to briefings.
Quarterly analysis of branded residence markets, new project launches and exclusive pricing data. No spam, ever.
Unsubscribe anytime. We respect your privacy.